US30 (Dow) Index CFD Trading Costs Explained (Spread, Point Value, Financing)
A US30 (Dow Jones Industrial Average) index CFD charges spread quoted in index points, commission on some account types, and an overnight financing charge for positions held past the daily cutoff — the same three cost 'buckets' as forex, but in a broker-defined point value rather than a standardized pip, since index CFDs are synthetic products without one universal contract size.
By CB-Dogs Editorial6 min read
Disclosure: CB-Dogs receives an advertising (referral) fee — sometimes called an IB commission — from brokers for accounts opened or linked through us, and returns part of it to you as cashback, the same model used by cashback and points sites. This does not change your trading costs.
On this page
- The short answer
- Component 1: the spread, quoted in points with a broker-defined value
- Component 2: commission
- Component 3: overnight financing, or a periodic rollover instead
- Worked example (illustrative numbers, financing-style model)
- When US30's cost tends to move the most
- Does a rebate apply to US30 trades?
- Related reading
- Frequently asked questions
- Work out your own numbers
Our EUR/USD vs. gold vs. indices comparison covers index CFDs as a generic category, deliberately naming no specific index, and our contract size and margin guide covers the general point-value convention without naming one either. Neither gives US30 — the CFD tracking the Dow Jones Industrial Average, one of the most widely traded index CFDs — its own dedicated cost breakdown. This article does that: its point-based spread, its broker-defined point value, its overnight financing mechanic, and a worked example.
Key takeaways
- A US30 index CFD tracks the price of the Dow Jones Industrial Average and charges spread in index points rather than forex pips, with each point's dollar value set by the broker rather than standardized across the industry.
- Index CFDs are synthetic products, not exchange-traded futures with one universal contract size — two brokers can assign different dollar values to a US30 point, so the same nominal point spread can mean a different dollar cost from one broker to the next.
- The overnight-holding cost on US30 is typically an interest-rate-benchmarked financing charge (applied to the position's notional value) rather than a currency-pair-style swap, and some brokers instead use a periodic futures-style rollover.
- US30 is commonly associated with spread widening and price volatility around US Federal Reserve decisions, major US corporate earnings releases, and scheduled US economic data, on top of general US equity market sentiment.
- A cashback rebate on US30 works the same way as on any other instrument: calculated on qualifying closed lot volume, not on spread, commission, or overnight financing paid — where it's offered depends entirely on your broker's own qualifying-instrument list.
The short answer
A US30 index CFD's trading cost is built from spread and commission using the same underlying logic as any instrument, but expressed in index points rather than forex pips or a metal's price points, using the general framework from our EUR/USD vs. gold vs. indices comparison. The overnight-holding component is where it differs most from forex: instead of a currency-pair swap rate, US30 (and index CFDs generally) commonly charge an interest-rate-benchmarked financing fee on the position's notional value, or, on some brokers, a periodic rollover tied to an underlying futures contract, the mechanic covered in our rollover and expiry costs guide.
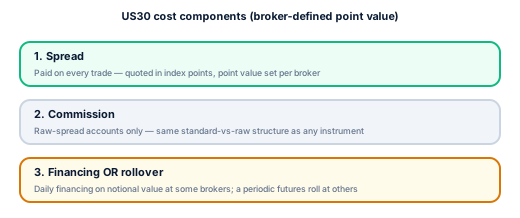
Total US30 cost ≈ (Spread in points × Point value × Lots) + (Commission per lot × Lots) + (Overnight financing — or periodic rollover, depending on your broker)
Component 1: the spread, quoted in points with a broker-defined value
Unlike a forex pair, where a pip is a standardized fraction of an exchange rate, a US30 index CFD's price moves in whole points, tracking the underlying Dow Jones Industrial Average level. Because index CFDs are synthetic products rather than exchange-traded futures with one universal specification, each broker sets its own dollar value per point — an illustrative convention might assign $1 per point at a 0.1 lot size (so $10 per point at a full 1.0 lot), but this is set individually by each broker and can differ meaningfully from one platform to the next, covered in general terms in our contract size and margin guide. US30's spread in absolute point terms is commonly wider than a forex pair's pip spread, which reflects the index's much higher price level (commonly in the tens of thousands of points) rather than necessarily a proportionally higher percentage cost.
Component 2: commission
Whether US30 carries a separate commission depends on account type, the same as any instrument. A standard account commonly folds cost into a wider spread, while a raw-spread or ECN-style account shows a tighter spread plus a disclosed per-lot commission, following the round-turn-vs-per-side conventions in our commission guide. Check your own broker's fee schedule for US30's specific commission figure rather than assuming it matches a forex pair's.
Component 3: overnight financing, or a periodic rollover instead
This is where US30 differs most from forex. Rather than a currency-pair interest-rate-differential swap, an index CFD's overnight-holding cost is commonly an interest-rate-benchmarked financing charge, applied to the position's full notional value (price × contract size × lots) once per day the position is held past the broker's daily cutoff — conceptually similar to swap but referencing a different underlying rate and typically expressed as an annualized percentage converted to a daily charge. Some brokers instead price their US30 CFD to track an underlying index futures contract directly, which rolls to the next contract periodically instead of charging daily financing — the mechanic covered in full in our rollover and expiry costs on index and commodity CFDs guide. Which model applies depends entirely on your specific broker, so check your platform's contract specification directly.
Worked example (illustrative numbers, financing-style model)
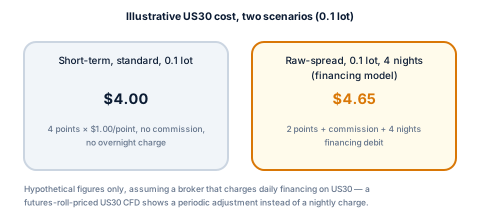
Example 1 — a short-term trade, standard account, 0.1 lot. Illustrative spread: 4 points, at an illustrative point value of $1.00 at 0.1 lot. Spread cost: 4 × $1.00 = $4.00, no separate commission, no overnight charge since the position closes the same session.
Example 2 — a raw-spread account, same 0.1 lot, held 4 nights, financing-style pricing. Illustrative spread: 2 points × $1.00 = $2.00. Illustrative commission: $2.50 per lot round turn × 0.1 lot = $0.25. Illustrative financing: −$0.60 per night × 4 nights = −$2.40 (a debit in this example). Total: $2.00 + $0.25 + $2.40 = $4.65.
All figures above are rounded, hypothetical inputs used to demonstrate the formula — not a real broker's spread, point value, commission, or financing rate for US30, and not a CB-Dogs cashback rate. A futures-roll-priced US30 CFD held over the same period wouldn't show a nightly charge at all — instead, a one-time price-level adjustment only if a roll date fell within the holding period, following the worked example in our rollover and expiry costs guide.
When US30's cost tends to move the most
US30 commonly sees its spread widen and its price move sharply around US Federal Reserve interest-rate decisions, major US corporate earnings releases (particularly from large index-weighted companies), and scheduled high-impact US economic data such as employment and inflation figures, on top of its general sensitivity to broad US equity market sentiment. It's also worth noting that a CFD broker's US30 trading hours commonly extend beyond the underlying New York Stock Exchange's regular session (sometimes close to 23 hours a day, 5 days a week), and liquidity — and therefore typical spread — can differ meaningfully between the underlying market's regular cash-session hours and the broker's extended-hours window. Our trading sessions guide covers the general session-liquidity pattern this reflects.
Does a rebate apply to US30 trades?
Cashback eligibility depends on your broker's own list of qualifying instruments, which commonly includes major index CFDs like US30 alongside forex pairs, gold, silver, and oil — check your specific broker's terms via our guide to how forex rebates work. As with any instrument, the rebate is calculated on qualifying closed lot volume, not on the spread, commission, or overnight financing you paid, so it functions as a partial offset against your combined US30 trading cost rather than a direct reduction of any one component.
Related reading
- NAS100 (Nasdaq 100) index CFD trading costs explained — the same cost-component breakdown applied to a tech-heavy index with a different point value and generally higher volatility.
- EUR/USD vs. gold vs. indices: comparing trading costs — the generic cross-instrument comparison framework this article's index-specific figures build on.
- Rollover and expiry costs on index and commodity CFDs — the full mechanics of the futures-roll model some index CFDs use instead of daily financing.
Frequently asked questions
No. A forex pip is a standardized fraction of an exchange rate with a broadly consistent dollar value convention across brokers. A US30 point's dollar value is set individually by each broker, since index CFDs are synthetic products without one universal contract size.
Work out your own numbers
Check your own platform's current US30 contract specification — spread, point value, commission structure, and whether it uses daily financing or a futures-style rollover for overnight positions — and plug it into the appropriate formula above for an accurate total. To see how qualifying volume adds up over time, try the cashback calculator, or register with CB-Dogs before your next trade.
Risk warning: forex and CFD trading carries a high risk of losing money. Cashback does not offset trading losses. Nothing here is investment advice.
Related articles
Cashback on your XM trades — free, paid in USDT
Sign up free